

 iscover


The Mortgage and Finance Association of Australia (MFAA) said the issue was not “a broker-specific problem” but rather “a challenge across the entire lending ecosystem”, encompassing lenders, bank direct channels, brokers, aggregators, referrers and introducers.
Ahead of an industry roundtable hosted by the Australian Securities and Investments Commission (ASIC), MFAA chief executive Anja Pannek said efforts to tackle mortgage fraud needed to extend beyond individual organisations, with greater information sharing required to identify suspicious activity and coordinate a response.
“Our shared focus must be on stopping fraud wherever it occurs and protecting consumers,” Pannek said.
“This is not something any one organisation can solve on its own. Success will require the support and participation of the entire lending ecosystem, with better information sharing to identify suspicious activity earlier and enable coordinated action.”
Pannek pointed to several existing initiatives that could help strengthen information sharing across the lending industry, including the Australian Financial Crimes Exchange initiative, the MFAA’s Referrer Risk Management Guidance and its longstanding advocacy for an ASIC portable unique identifier.
The latter, she said, would strengthen reference checking and information sharing as individuals move between organisations and roles.
She added that any new framework would need to be proportionate and address risks across all lending channels, rather than introducing further obligations without a clear purpose.
“Any new framework must be informed by evidence, proportionate and address risks across all lending channels. Meaningful consultation, clear governance, appropriate safeguards and recognition of existing regulatory obligations will be essential to its success,” Pannek said.

She described the ASIC roundtable, scheduled for 16 November, as an opportunity to advance the discussion, encouraging participants to bring forward ideas and proposals.
“Monday’s ASIC roundtable is an opportunity to advance this work together. We encourage everyone attending to bring their ideas and proposals to the discussion, with a shared commitment to practical solutions that protect consumers, support those doing the right thing and strengthen confidence across our lending system.”
The comments come amid growing calls for greater collaboration across the industry to identify misconduct and prevent fraudulent operators from moving between organisations and re-entering the sector.
They also follow heightened scrutiny of mortgage fraud, with a number of high-profile cases and investigations bringing the issue into sharper focus.
Brokers weigh in on conduct register proposal
Pannek’s comments come after the proposal from fellow association Finance Broker Association of Australia for a centralised, independent national conduct register that could allow lenders, aggregators and other parties to check the professional conduct history of brokers.
Among brokers who have weighed in on the proposal, there has been support for greater transparency and accountability, although questions remain over the practical value of a register and how it would be funded.
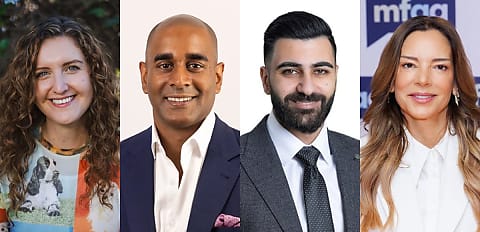
Katie Norbury, founder of Settle In Home Loans, told Broker Daily that she supported the idea of a centralised register, arguing it could give consumers greater transparency.
“Choice is at the core of mortgage broking: access to different lenders, policies and solutions that suit each client’s circumstances,” she said.
“A centralised, independent register would strengthen that principle, helping consumers choose a broker whose values align with their own.”
However, Norbury questioned whether consumers would use the register and who would bear the cost of establishing and promoting it.
“I would assume my potential clients are more likely to search me on Google reviews rather than a centralised register.
“My key questions would be, how are we advertising this register to potential clients, and who is footing the bill to build and advertise it?”
Aaron Christie-David, managing director of Atelier Wealth, was more firmly behind the proposal, arguing it could help professionalise the industry and weed out poor operators.
“I absolutely think this is necessary in terms of making our industry much more professional,” he said.
“Good operators will have nothing to worry about. The bad operators will certainly see this as a way to weed them out as well.”
Christie-David said he would also be comfortable with brokers bearing some of the cost of establishing the register, provided it helped improve standards across the industry.
“If it means the cost of doing business goes up for a broker to pay for something like this, because it has to be paid somewhere, I think I’d be fairly comfortable with that as well.”
Fairness remains a concern
Nicholas Hakim, director of Skyline Brokers, said a central register could help address gaps in existing systems, but warned it would need to distinguish between substantiated misconduct and allegations or commercial disputes.
“We are already in a heavily regulated space. We have ASIC oversight, lender accreditation, aggregator compliance and formal reference checks. The real question is whether these different systems are actually talking to each other,” he said.
“If a centralised register can boost transparency, flag real misconduct, and stop people from jumping from one firm to another to dodge accountability, then I can see the value in it.”
However, Hakim warned the system could become an “industry blacklist” without adequate safeguards.
“There is a massive difference between proven misconduct and a simple allegation, a compliance hiccup, or a dispute with a lender. Just because a lender decides to suspend or end someone’s accreditation doesn’t mean that broker did anything wrong,” he said.
“Without proper safeguards, brokers could end up facing serious financial and reputational damage."
[Related: Industry welcomes BID review but defends broker judgement]
 Want to see more stories from trusted news sources?
Make Broker Daily a preferred news source on Google.
