

 iscover

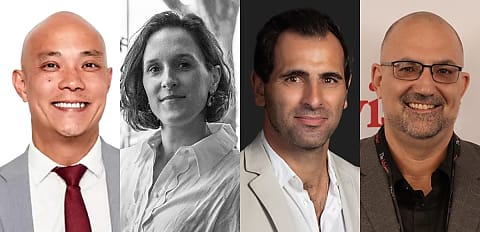

“If choosing a home loan were simply about the lowest rate, comparison websites would have replaced brokers years ago.”
That was the verdict of one broker speaking to Broker Daily following the Australian Securities and Investments Commissions’ (ASIC) first comprehensive review of best interests duty since its introduction in 2021.
The Mortgage brokers: Review of best interests duties and complaints handling practices report examined 13 credit licensees across eight major aggregator groups, identifying concerns around brokers not recommending the cheapest loans, providing only one loan option, underreporting complaints and the use of artificial intelligence in the industry.
While brokers acknowledged the need for strong compliance and oversight, they argued that the findings needed to be considered in the context of individual client needs, lender suitability and the judgement involved in recommending a home loan.
The cheapest loan is not always the right loan
ASIC’s finding that borrowers were not recommended the cheapest available loan in 20 per cent of cases drew particular attention from brokers, who said price was only one consideration when assessing a loan’s suitability.
Kit Johnson, Aussie broker for Forest Lake, Queensland, said he had already seen two clients choose to pay more than $50 extra a month to borrow with a major bank since the review was released.
“They understood there was a cheaper option and valued those benefits,” he said.

Johnson said second-tier lenders had featured heavily in his recommendations for years, but more competitive pricing from the major banks and a shift in customer appetite had changed the landscape.
“I think HSBC’s retail exit and Suncorp’s move to ANZ are contributing to that; customers want consistency and security during these market changes.
“Products, features and banking arrangements can change in the confusion, and many customers are placing more value on familiarity and continuity.”
Finni broker Eva Loisance similarly argued that assessing a loan solely on its headline rate overlooked the reasons borrowers seek professional advice.
“If everyone could just get the cheapest home loan online, you know, there’d be no need for the broker. Broker would not exist,” Loisance said.
“People want the cheapest option. We want to give them the cheapest option. Most of the time it’s not applicable for hundred different reasons.
“Sometimes we even refinance people onto more expensive options, but there’s always a reason behind it.
“I have never liked the idea of solely looking at the cheapest options, it ignores the nuance of why people come to brokers.”
The report also found that 6.8 per cent of clients received only one loan option. Fellow Finni broker Costa Arvanitopoulos said this could reflect the limited options available to borrowers rather than a failure to consider alternatives.
“I think a lot of those people in that 6.8 per cent would be because they’ve reached the end of their portfolio capacity, they’ve done everything they could and then there’s only one lender that’s available.
“To give some choice, what our aggregator has told us to do is to present three products from that same lender instead, so if there really aren’t many options, there is still some level of choice.”
Brokers urged to keep AI in check
ASIC also raised concerns about the use of automated decision-making tools and AI, warning of compliance risks where technology is adopted without adequate oversight.
For brokers, ASIC said the challenge is ensuring technology supports the recommendation process without replacing the checks and professional judgement required under BID.
Nick Chong, founder and director of Sydney-based brokerage Rateseeker, said automated tools could overlook important details when comparing home loans.
“These tools are only as good as their data, and they can miss temporary discounts, cashbacks or fee waivers that a broker would catch manually,” he said.
“If you rely on the ranking without checking it, you may be recommending incomplete information.”
Johnson said he had also seen AI misinterpret lender policy, cautioning against relying on it entirely when advising borrowers.
“It is an amazing tool and keeps improving but relying on it completely when advising customers on decisions with long-term consequences is very risky in my opinion, for the moment anyway,” he said.
ASIC also cautioned against software features that allow brokers to insert generic, auto-populated rationale into client files.
Chong said the convenience of automated documentation should not come at the expense of properly recording why a recommendation suited a particular borrower.
“I wouldn’t say AI has made brokers lazy as a group, but any tool that auto-fills a rationale makes it tempting to stop thinking. The note should come from a real conversation about what the client wants.
“Technology can speed up the admin, but the judgement and the accountability stay with the adviser.”
Calls for greater clarity on complaints
ASIC identified underreporting of internal dispute resolution (IDR) complaints, both by individual brokers to aggregators and by aggregators to the regulator.
It recommended that licensees improve their complaint identification processes and ensure accurate IDR data is reported.
Chong agreed that brokers needed to be diligent, but said clearer guidance would help businesses identify when a client interaction should be recorded as a complaint.
“A broker who smooths over a frustrated client on the phone may not realise that counts as a complaint,” he said.
“Clearer examples of what to log, and when, would help smaller businesses in particular.”
Johnson praised his aggregator’s existing complaints policies and escalation procedures but questioned how consistently those processes were being followed across the industry.
He also called for more practical guidance on BID, including what evidence supports recommending a higher-cost loan when a borrower prioritises factors such as convenience, service or particular features.
“On BID, practical examples would help demonstrate what evidence adequately supports a higher-cost recommendation, particularly where customers value convenience, service, or specific features.
“I would also have liked a clearer breakdown of where weaknesses were concentrated and which supervision arrangements were working well.
“More detail would help target improvements and provide consumers with more useful information about the oversight of their broker.
“The report should have made a much clearer distinction between the vastly different business models in the aggregator space.”
[Related: Industry welcomes BID review but defends broker judgement]
 Want to see more stories from trusted news sources?
Make Broker Daily a preferred news source on Google.
