
 iscover


The Mortgage and Finance Association of Australia’s (MFAA) Global Insights Report 2026 examined broking in the US, Canada, the UK, the Netherlands and Germany, comparing how each market approaches regulation, remuneration, technology, emerging risks and broker business models.
The report found that Australia had strong foundations, including high broker market share, established technology infrastructure, a mature aggregation sector and a robust regulatory framework.
However, it also identified opportunities to strengthen professionalism, improve consumer outcomes and explore different business and remuneration models.
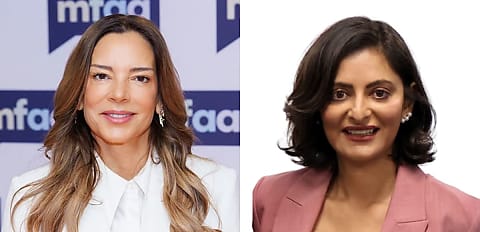
MFAA CEO Anja Pannek said: “With mortgage brokers facilitating 81.6 per cent of new residential home lending in the June 2026 quarter, Australians continue to demonstrate considerable confidence in the broker channel.
“We wanted to look beyond our own market, test our assumptions and understand what we could learn from others. Bringing those insights back to members is part of how we support their businesses and contribute to an informed conversation about the industry’s future.”
Overseas brokers take a broader approach to advice
One key difference identified in the report was the broader range of services offered by mortgage advisers in some overseas markets.
In the UK and the Netherlands, advisers commonly provide guidance beyond the mortgage transaction, including insurance, protection products, retirement planning and broader financial considerations.

The report said the concept of “mortgage advice” was “deeply embedded within both regulatory frameworks and consumer expectations” in these markets.
Similar trends were identified in Canada and Germany, where many advisers operate within broader financial services businesses.
By contrast, the report said: “Australia remains somewhat unique in maintaining a relatively specialised mortgage broking model, with a stronger distinction between mortgage advice and broader financial advice.”
The report also highlighted professional standards as a key differentiator across markets, with Australia’s regulatory framework comparing favourably with those examined.
“The combination of national licensing, responsible lending obligations, external dispute resolution, ongoing professional development requirements and the Best Interests Duty provides a robust framework that is broadly consistent with international best practice,” the report said.
“Importantly, several international stakeholders expressed interest in Australia’s approach to broker regulation and the role brokers play in supporting competition and consumer choice.”
MFAA policy and legal executive Naveen Ahluwalia said: “Australia is one of three jurisdictions internationally including the Netherlands and the United Kingdom with mortgage broker market share above 80 per cent.
“Our research highlights robust consumer protections, effective regulation and high professional standards underpin competitive mortgage markets and a strong broking sector.”
No single remuneration model guarantees success
The report also found significant differences in how mortgage advisers are paid across the markets examined, but said remuneration structures alone “do not determine the success of a broker market”.
Instead, broker market share, consumer trust, competition and consumer outcomes were shaped by a broader combination of regulatory settings, professionalism, consumer awareness, technology adoption and market structure.
Australia, Canada, the UK, Germany and the US primarily operate lender-funded remuneration models, although commission levels, clawback arrangements, ongoing payments and the ability to charge consumers directly vary.
The Netherlands stands apart, having introduced a consumer-pays model for mortgage advice following concerns about commission-driven financial product distribution.
Following financial product mis-selling scandals and concerns about opaque commission structures, the Dutch Government introduced reforms that prohibited commissions for complex financial products, including mortgages.
Despite initial concerns about consumer access to advice, mortgage advisers continue to play a significant role in the Dutch home lending market, with brokers facilitating around 80 per cent of residential mortgage transactions.
Australia also differs from many overseas markets because ongoing trail commission remains a standard feature of broker remuneration. In several other jurisdictions, payments are largely concentrated at origination, with little or no ongoing remuneration after settlement.
The report said Australia’s prevalence of variable-rate lending created opportunities for ongoing customer engagement, with brokers often maintaining relationships with clients through refinancing, loan restructuring and broader lending discussions.
Several international stakeholders expressed interest in the role trail commissions play in supporting these ongoing relationships.
Scale matters, but smaller businesses can compete
The report identified consolidation and the emergence of larger, more sophisticated broker businesses as trends across several markets.
It said scale could support investment in technology, cyber security, compliance, specialist expertise, marketing and operational support.
However, size alone did not determine success. Smaller businesses could continue to compete through specialised expertise, strong customer relationships and clear value propositions.
The report pointed to Mortgage Advice Bureau (MAB), one of the UK’s largest intermediary businesses, as an example of how scale can support advisers without losing the personal element of advice.
MAB uses adviser networks, technology platforms, compliance support and operational infrastructure to support mortgage advisers across the country, while maintaining a focus on personalised advice and customer support.
The report concluded: “MAB demonstrates that growth and scale do not necessarily require a move away from relationship-based advice.
“Instead, scale can be used to strengthen service delivery, improve consistency and create capacity for mortgage advisers to focus on customer outcomes.”
Fraud and scams require industry-wide action
Fraud, scams and cyber threats were common challenges across all five markets examined, with the report warning that increasingly sophisticated risks would require greater industry-wide cooperation.
While traditional methods such as income manipulation and document falsification remained prevalent, the report said more sophisticated approaches involving synthetic identities, organised criminal networks and digitally altered documents were becoming increasingly common.
Scams were also evolving, with impersonation, payment redirection, business email compromise and social engineering identified as growing threats during property transactions.
The report said these risks could involve multiple parties, including brokers, lenders, accountants, lawyers, conveyancers, real estate agents and technology providers.
Indeed, Australia has recently seen a string of high-profile fraud cases linked to technology and AI, while one in seven Australians experienced a scam in 2024–25.
It added: “Importantly, many stakeholders noted that fraud is becoming harder to detect through traditional controls alone. As a result, greater emphasis is being placed on data sharing, behavioral analytics and collaborative intelligence frameworks.
“The international experience suggests that prevention efforts will become increasingly dependent on collaboration across lenders, aggregators, brokers, regulators and other participants within the lending ecosystem.”
The report also covered the developments of technology across overseas markets. Read Friday's (23 October) technology bulletin for coverage.
[Related: Broking leaders unpack lessons from international markets]
 Want to see more stories from trusted news sources?
Make Broker Daily a preferred news source on Google.
